Allowable Expenses for Landlords in the UK: What You Can & Can’t Claim
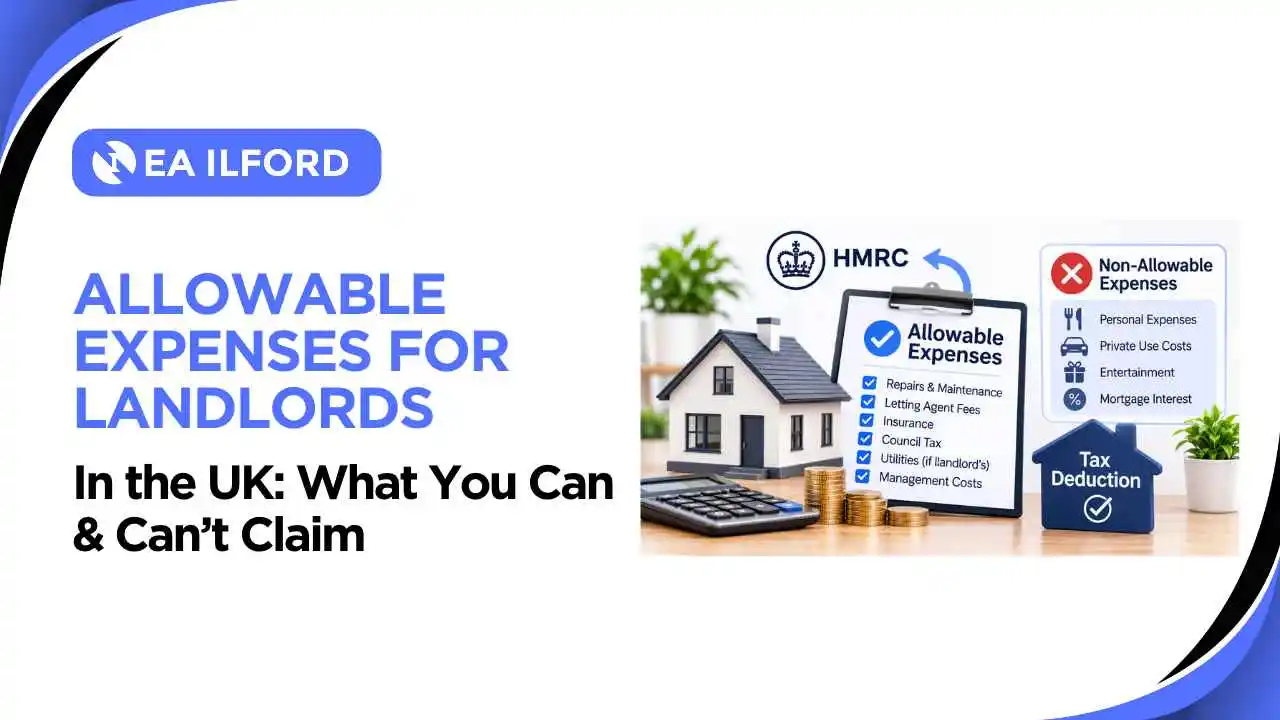
Can I claim the boiler repair and the agent’s fees, or will HMRC reject it? If you have a similar question, then you’re not alone. Most landlords know some costs can be claimed, but not which ones. Allowable expenses for landlords are the running costs of a rental property that you can deduct before tax. This informational guide from Estate Agents Ilford shows which ones count and how to claim them.
What are Allowable expenses for Landlords?
Allowable expenses for landlords are the costs of running a rental property that you can take off your rental income before you pay tax. You pay tax on your profit, not on the rent itself, so every cost you claim correctly means less tax to pay. These expenses form the basis of landlord tax deductions.
The difficult thing is knowing what counts as allowable. For example, fixing a leaking pipe is okay to deduct, but adding an extension isn’t. Mortgage Interest are used to be fine, but they’re not treated as an allowable deduction anymore. Let’s see what allowable deductions for landlords in the UK are according to HMRC.
| What does “Wholly and Exclusively” mean? HMRC only lets you claim a cost for allowable expenses for landlords if you spent it entirely for the rental business. If the money was partly for your own benefit, it fails the test called the wholly and exclusively test. For example, a bill to fix a pipe leak in the tenant’s bathroom will pass this test, but a bill fixing your own kitchen tap doesn’t, unless you split the invoice claim and claim only part related to the rental business. |
List of Allowable Expenses for Landlords in the UK
Landlords can claim various expenses against their rental income, provided they meet HMRC rules. The table below covers the list of main allowable expenses, what you can claim, and any conditions that apply.
Expense | What’s claimable? | Conditions |
Management fees | Letting and property management fees. | Must relate to the rental business. |
Legal fees | Qualifying tenancy and eviction costs. | Property purchase and sale fees are excluded. |
Repairs and maintenance | Plumbing, roofing, boiler repairs and redecoration. | Repairs qualify; improvements do not. |
Advertising | Tenant-finding adverts, listings and photography. | Must relate to finding tenants. |
Buildings insurance | Landlord buildings insurance premiums. | Must cover the rental property. |
Contents insurance | Insurance for landlord-owned furnishings. | Must relate to the let property. |
Wages | Payments to cleaners, gardeners and employees. | Must be genuine business costs. |
Safety and licensing | Gas checks, EICRs and licence fees. | Must relate to the rental property. |
Service charges | Communal maintenance and management charges. | Landlord-paid amounts only. |
Utilities | Gas, electricity and water bills. | Only costs paid by the landlord. |
Cleaning | Cleaning between tenancies. | Must be the landlord’s responsibility. |
Phone costs | Business-related mobile phone expenses. | Personal use is excluded. |
Travel and mileage | Property inspections and maintenance visits. | Business journeys only. |
Professional subscriptions | Relevant landlord association fees. | Must support the rental business. |
Ground rent and council tax | Landlord-paid ground rent and council tax. | Only qualifying rental property costs. |
Bad debts | Qualifying irrecoverable rent and recovery costs. | Depends on the accounting basis. |
Replacement items | Qualifying replacement furniture and appliances. | Initial purchases are excluded. |
Administration | Postage, stationery and accounting software. | Must be rental-business expenses. |
What Landlords Can Claim As Allowable Expense?
Below is the detailed breakdown of allowable expenses for landlords in the UK:
Management Fees
Landlords who use any letting agent to manage their property can deduct property management fees for tenant finding, rent collection and ongoing property management.
The management fees must be related to the day-to-day running of the rental property. However, costs connected to buying and selling a property don’t qualify as ordinary allowable expenses for landlords.
Advertising for Tenants and Viewings
Marketing and advertising costs for finding new tenants are allowable rental expenses. It includes property listing, online advertisements, professional photography, and associated tenant-finding marketing. Landlords can also claim qualifying costs directly associated with arranging viewings. The expense must relate to letting the property rather than promoting a property sale.
Legal Fees
Some legal costs can be deducted when they are directly related to the rental business. Those costs include qualifying tenant agreements for lets of one year or less or lease renewals for less than 50 years. Legal fees for purchasing a property aren’t allowable against your rental income in the UK. Landlords should keep invoices showing the work carried out.
Property Maintenance and Repair
Landlords in the UK can claim the cost of maintaining a property and repairing damage caused by normal wear and tear or unexpected accidents. For example, fixing a leaking pipe, replacing a broken tile, repairing a boiler, and repainting walls between tenancies are allowable expenses for landlords.
But the condition of these being allowable is that work must restore the property rather than significantly improve the condition. For example, replacing a broken kitchen unit with a similar modern equivalent may qualify for the test. On the other hand, a higher-specification kitchen is generally not allowable.
Insurance Premium: Building & Contents Insurance
Premiums paid for buildings insurance on their rental properties can be claimed as allowable expenses for landlords. It usually covers risks such as fire, flooding, storm damage, and other insured damage to the structure.
Moreover, contents insurance is also an allowable expense when it covers furniture, appliances, and other belongings provided for tenants by landlords. The only portion of the premium related to the rental business can be claimed if the property has mixed personal and rental use.
Services Charges
As a landlord of a leasehold property, you can also claim service charges paid for the upkeep of the communal areas and shared facilities. It includes cover cleaning, lift maintenance charges, communal lighting costs, gardening and building management costs. The amount that the landlord is responsible for is deducted from their rental income.
Utilities Paid by Landlords
You can claim it when you pay it as landlord. If the tenant is responsible for gas, electricity, water and broadband bills, there’s nothing to claim. If you pay them, for example, during a void period or because the rent includes bills, they count as allowable expenses. Keep the records of supplier statements and note which dates the property was empty, so you can show HMRC why you were paying.
Cleaning Costs
End of tenancy cleaning, cleaning between tenancies, cleaning communal areas in a block, and cleaning the property for new tenants after a repair all are allowable expenses. A one-off deep clean for a new let sits within the wholly and exclusively rule. If you stay in the property between lets, claim only the cleaning that relates to the rental.
Mobile Phone Costs
You can only claim the part used for the rental, such as calls to tenants and contractors or messages with your letting agent. A separate SIM or a cheap second number for the rental makes this much simpler.
Mileage for Property Management & Travelling
The cost of travel, such as inspecting the property, meeting a tenant, collecting keys or going to a contractor. HMRC Property Income Manual gives 55p per mile for the first 10,000 business miles and 25p for each additional mile when using a car or van in the 2026/27 tax year. The rate for motorcycles is 24p per mile.
Landlords can use either the mileage rate or actual running costs for the same vehicle, not both. Bus, train and parking fees for those trips are claimable on top.
Professional Subscriptions
Membership fees for bodies that relate directly to your letting business, such as a landlord association or an accreditation scheme, can generally be claimed as allowable expenses for landlords. Subscriptions that cover other work or personal interests can’t, even if they’re loosely related to property.
Ground & Council Tax
If you own a leasehold property/flat, the ground rent and any service charges you pay are allowable. Council Tax is claimable only when the landlord pays it. If the tenant pays the council tax, you have nothing to claim.
Bad Debts and Rent Arrear Recovery
It’s the most complicated when considering allowable expenses for landlords. Most individual landlords now use the cash basis. Unpaid rent is therefore not included as taxable income, so you cannot claim it again as a bad debt. What you can usually claim are the costs of recovering the arrears, such as legal fees for chasing the tenant.
Administrative Expense
Small running costs of the rental count here,e such as postage, printing tenancy documents, accounting software and back charges on an account used for the rental. They look minor, but when you add them over a year, they’re the ones landlords usually forget to claim. If you use the property income allowance instead, you can’t claim any of them, so work out which option saves more.
How to Claim Allowable Expenses?
You don’t claim allowable expenses for landlords through a separate application. You claim them by entering them on your Self Assessment return.
- First, check the cost that qualifies to claim. It must pass the wholly and exclusively test and must be a running cost of a rental, not an improvement.
- Then make sure to keep the evidence of each invoice, receipts, and bank statements, and note what each one is for, including void period costs.
- Add up the tax year. Total your rental income and your allowable expenses for 6 April to 5 April of the respective year you’re calculating for.
- Compare the £1,000 property allowance. When your actual expenses are lower, the allowance can save you more, but you can’t use both.
- Fill in the SA105 UK property supplementary pages and file them with your main tax return. Enter your total rental income and your allowable expense.
- Submit and pay. Send the return and pay any tax by 31 January after the tax year ends.
What Counts as Non-Allowable Expenses for Landlords?
Some costs may appear to belong to your rental on your tax return, but they can’t be claimed as allowable expenses for landlords under HMRC’s rules.
Expense | Why it’s not claimable | Instead |
Capital expenditure and improvements | It improves the property rather than maintaining it | Counts towards Capital Gains Tax |
Costs with a personal element | Fails the “wholly and exclusively” test | Claim the rental share only |
Finance costs | Not deductible for individual landlords | 20% tax credit |
Pre-letting expenses | Some costs may qualify, but personal and capital expenses are excluded. | Claim qualifying revenue expenses incurred within seven years before the rental business starts. |
Home office costs | The rental-business share of qualifying household costs. | Claim only a space used solely for the rental business. |
Uncommercial lettings | Expenses may be restricted when letting to family or friends on uncommercial terms. | Claim expenses only up to the rent received. Excess costs cannot be carried forward. |
Mortgage capital payments | Repaying the loan isn’t a running cost | None |
Purchase costs | Part of buying the asset | Counts towards Capital Gains Tax |
Sale costs | Part of disposing of the property | Deducted from your gain |
Fines and penalties | Not a normal cost of running the rental | None |
Important Note: Preletting costs are not flat-rate for a claim. Costs you pay up to seven years before your first let can sometimes be claimed as if you paid them on the day letting began, but not if they relate to the period you lived there, so check the rules first.
Capital vs Revenue Expenditure
Revenue expenditure is the everyday cost of keeping a rental in working order, like fixing a boiler or repainting between tenants. You can deduct it as allowable expenses for landlords from rental income in the year you pay it.
Capital expenditure improves the property or adds something new, like an extension or a better kitchen. You can’t deduct it from rental income. For more detail, see our guide to capital and revenue expenditure.
Finance Costs and Mortgage Interest for Landlords
Mortgage interest is one of the highest costs of owning a rental, but it isn’t treated like the other expenses. Claiming can depend on whether you own the property personally or through a limited company.
Section 24 and the 20% Tax Credit
If you own a rental in your own name, you cannot deduct mortgage interest from your rental income. This is Section 24. You pay tax on your profit before interest, then claim a tax reduction worth 20% of your finance costs, taken off your final bill. From April 2027, this relief will be calculated at the new 24% property basic rate, which doesn’t apply to the 2026/27 year.
The credit is limited to the lowest of your finance costs, your property profits or your income above the personal allowance.
Limited Company Treatment
Section 24 doesn’t apply to limited companies. A company deducts its mortgage interest as a business expense before working out corporation tax. That’s why many landlords consider buying a property through a company, though moving existing property can trigger stamp duty and capital gains tax. It’s better to take experts’ advice first.
Exceptions and Relief for UK Landlords
There are some costs that normally can’t be claimed or income that would normally be taxed that get special treatment. These are the three types of relief landlords use most.
Replacement of Domestic Items Relief
If you replace a worn-out item in a residential let, you can claim the cost of a like-for-like replacement under Replacement of Domestic Items Relief. It covers furniture and household items in a residential let such as a sofa, fridge, washing machine, carpets or curtains. Fixtures like boilers and bathroom suites don’t qualify, because they’re treated as repairs or improvements.
Who Qualifies for Relief: You can qualify if you let a residential property and replace an item that was already provided in it.
How to Claim the Relief: Enter the cost of replacement in the expenses section of your SA105 for the year you bought. Keep the receipt and a note of what it replaced.
Property Income Allowance
Landlords can deduct a flat £1,000 from their rental income instead of claiming their actual expenses. It suits landlords with low costs. If your income is £1,000 or less, you don’t need to report it. Moreover, you cannot claim the £1,000 allowance and actual expenses against the same rental income.
Rent a Room Relief
The rent-a-room scheme allows you to earn a tax-free income from letting a furnished room in your main home. You can earn up to £7,500 a year tax-free, depending on the scheme conditions.
Eligibility for rent-a-room relief:
- You must let out a furnished room.
- The property must be your main or only residence.
- The room can be in a house, flat or other residential accommodation.
- You can let the room to a lodger or a paying guest.
- The tax-free limit is £7,500 per year, or £3,750 if you share the rental income with someone else.
How Making Tax Digital Changes Reporting Taxes?
Making Tax Digital (MTD) changes how landlords report rental income and expenses to HMRC. You can maintain your records throughout the year and report the relevant totals quarterly using government-compatible software.
The new rules are being introduced in stages, depending on your total qualifying income from property and self-employment before expenses.
Annual qualifying income | Start date |
Over £50,000 | 6 April 2026 |
Over £30,000 | 6 April 2027 |
Over £20,000 | 6 April 2028 |
The rules on which allowable expenses for landlords you can claim do not change. However, qualifying landlords must keep digital records of their rental income and expenses and include them in quarterly updates to HMRC.
For example, you will need to:
- Record property repairs and maintenance costs.
- Record letting agent and property management fees.
- Keep records of insurance premiums and property licensing fees.
- Record allowable legal and professional fees.
- Separate allowable expenses from personal or non-deductible costs.
- Keep invoices, receipts and bank statements as supporting evidence.
Conclusion
If you keep tracking allowable expenses for landlords, you can reduce your taxable income and avoid paying more tax than necessary. If managing property costs and maintenance feels time-consuming, a property management service can help with day-to-day responsibilities and keep your rental arrangements organised.